Quantitative EventDriven Modeling BTC Balance Sheet Shocks with SEC EDGAR Filings in R
News Source : R-bloggers.com
News Summary
- This technical article explores an end-to-end, reproducible quantitative pipeline built in R.
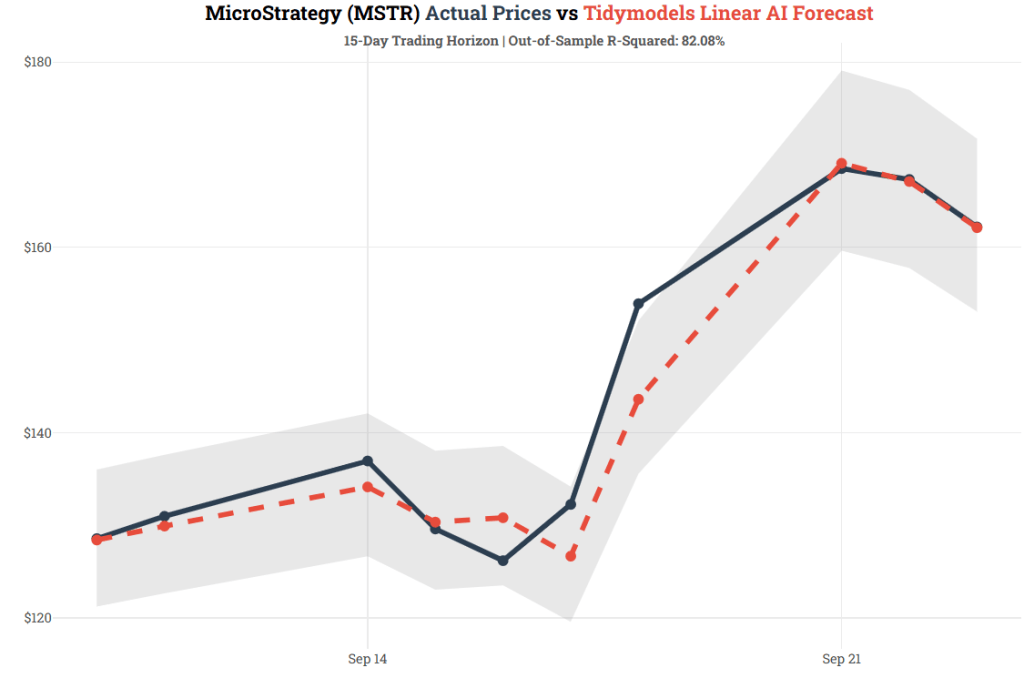
- It ingests real-time SEC EDGAR filings, dynamically extracts digital asset balance sheet facts, aligns mixed-frequency financial and market data, and models MSTR daily equity log returns.
- The pipeline follows a modern, production-grade functional programming architecture using the tidyverse ecosystem.
- The Structural Model achieved an out-of-sample R-Squared of 82.08%, significantly outperforming the Naive Baseline.
[This article was first published on DataGeeek, and kindly contributed to Rbloggers]. (You can report issue about the content on this page here) Want to share your content on Rbloggers?








 Never miss a story from us, subscribe to our newsletter