Semiparametric option pricing based on underlyings historical data (accepted at the osQF 2026 (ex R/Finance) conference)
News Source : R-bloggers.com
News Summary
- This post is a follow-up to my previous posts on semi-parametric option pricing.
- A link to the study (accepted for presentation at the osQF 2026 conference) is provided at the end of this post.
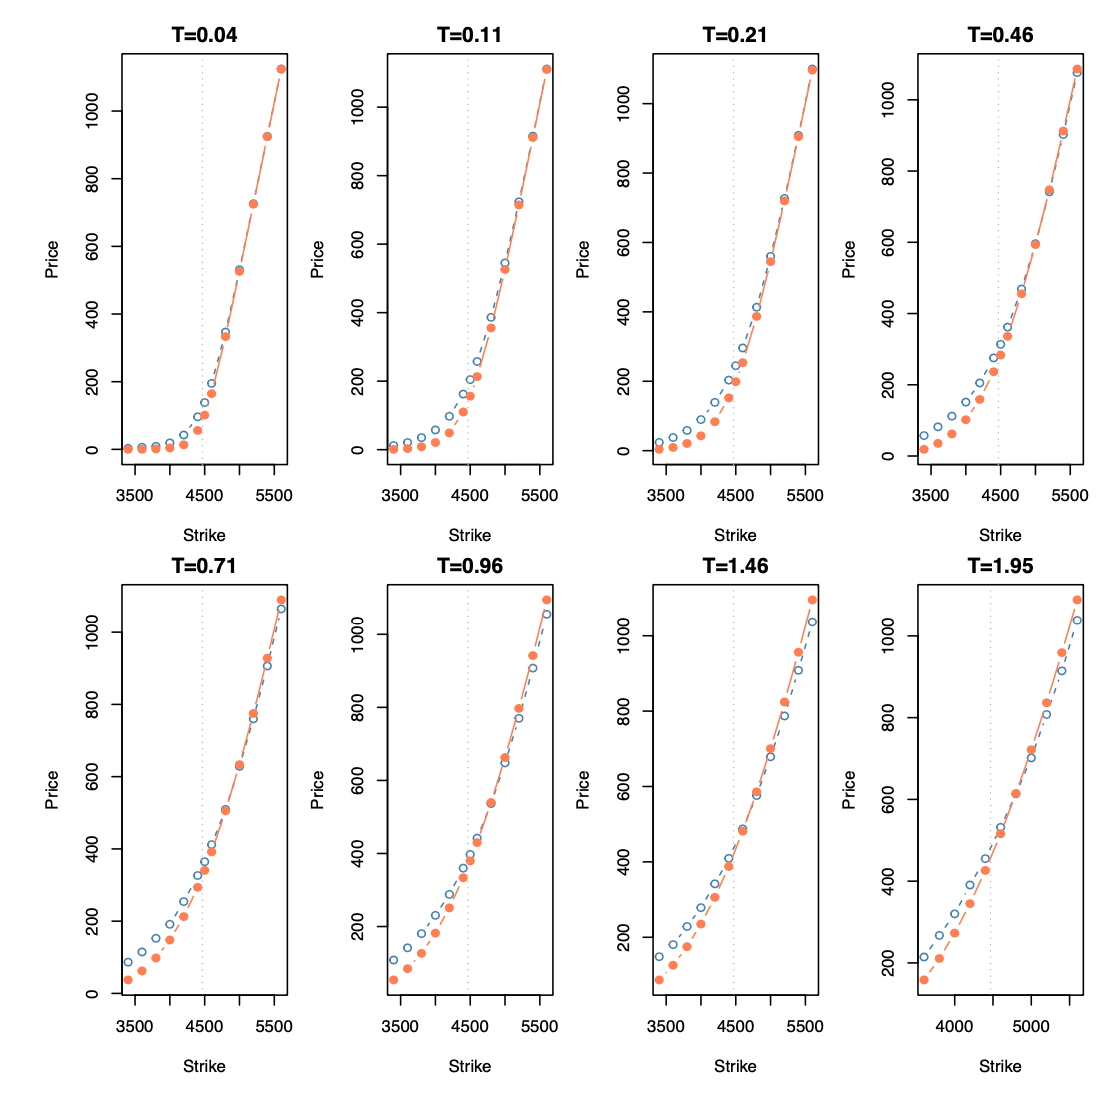
- In this study, we build an empirical pricing measure for options directly from their underlying’s historical dynamics, requiring no market of option prices to calibrate against.
- Because the construction requires no option-market input at any stage, it extends naturally to path-dependent payoffs.
This post is a followup to my previous posts on semiparametric option pricing. A link to the study (accepted for presentation at the osQF 2026 conference) is provided at the end of this post.







 Never miss a story from us, subscribe to our newsletter